Conventional wisdom suggests that volumes within the Bond markets change throughout the year. But does the old adage Sell in May and go away1 really stand up in the modern era?


It almost seems accepted that summer volumes are lower than November - April, however, does this stand up to inspection, in Chart 1 below, we take a look at volume grouped in quarters for the last 4 years.
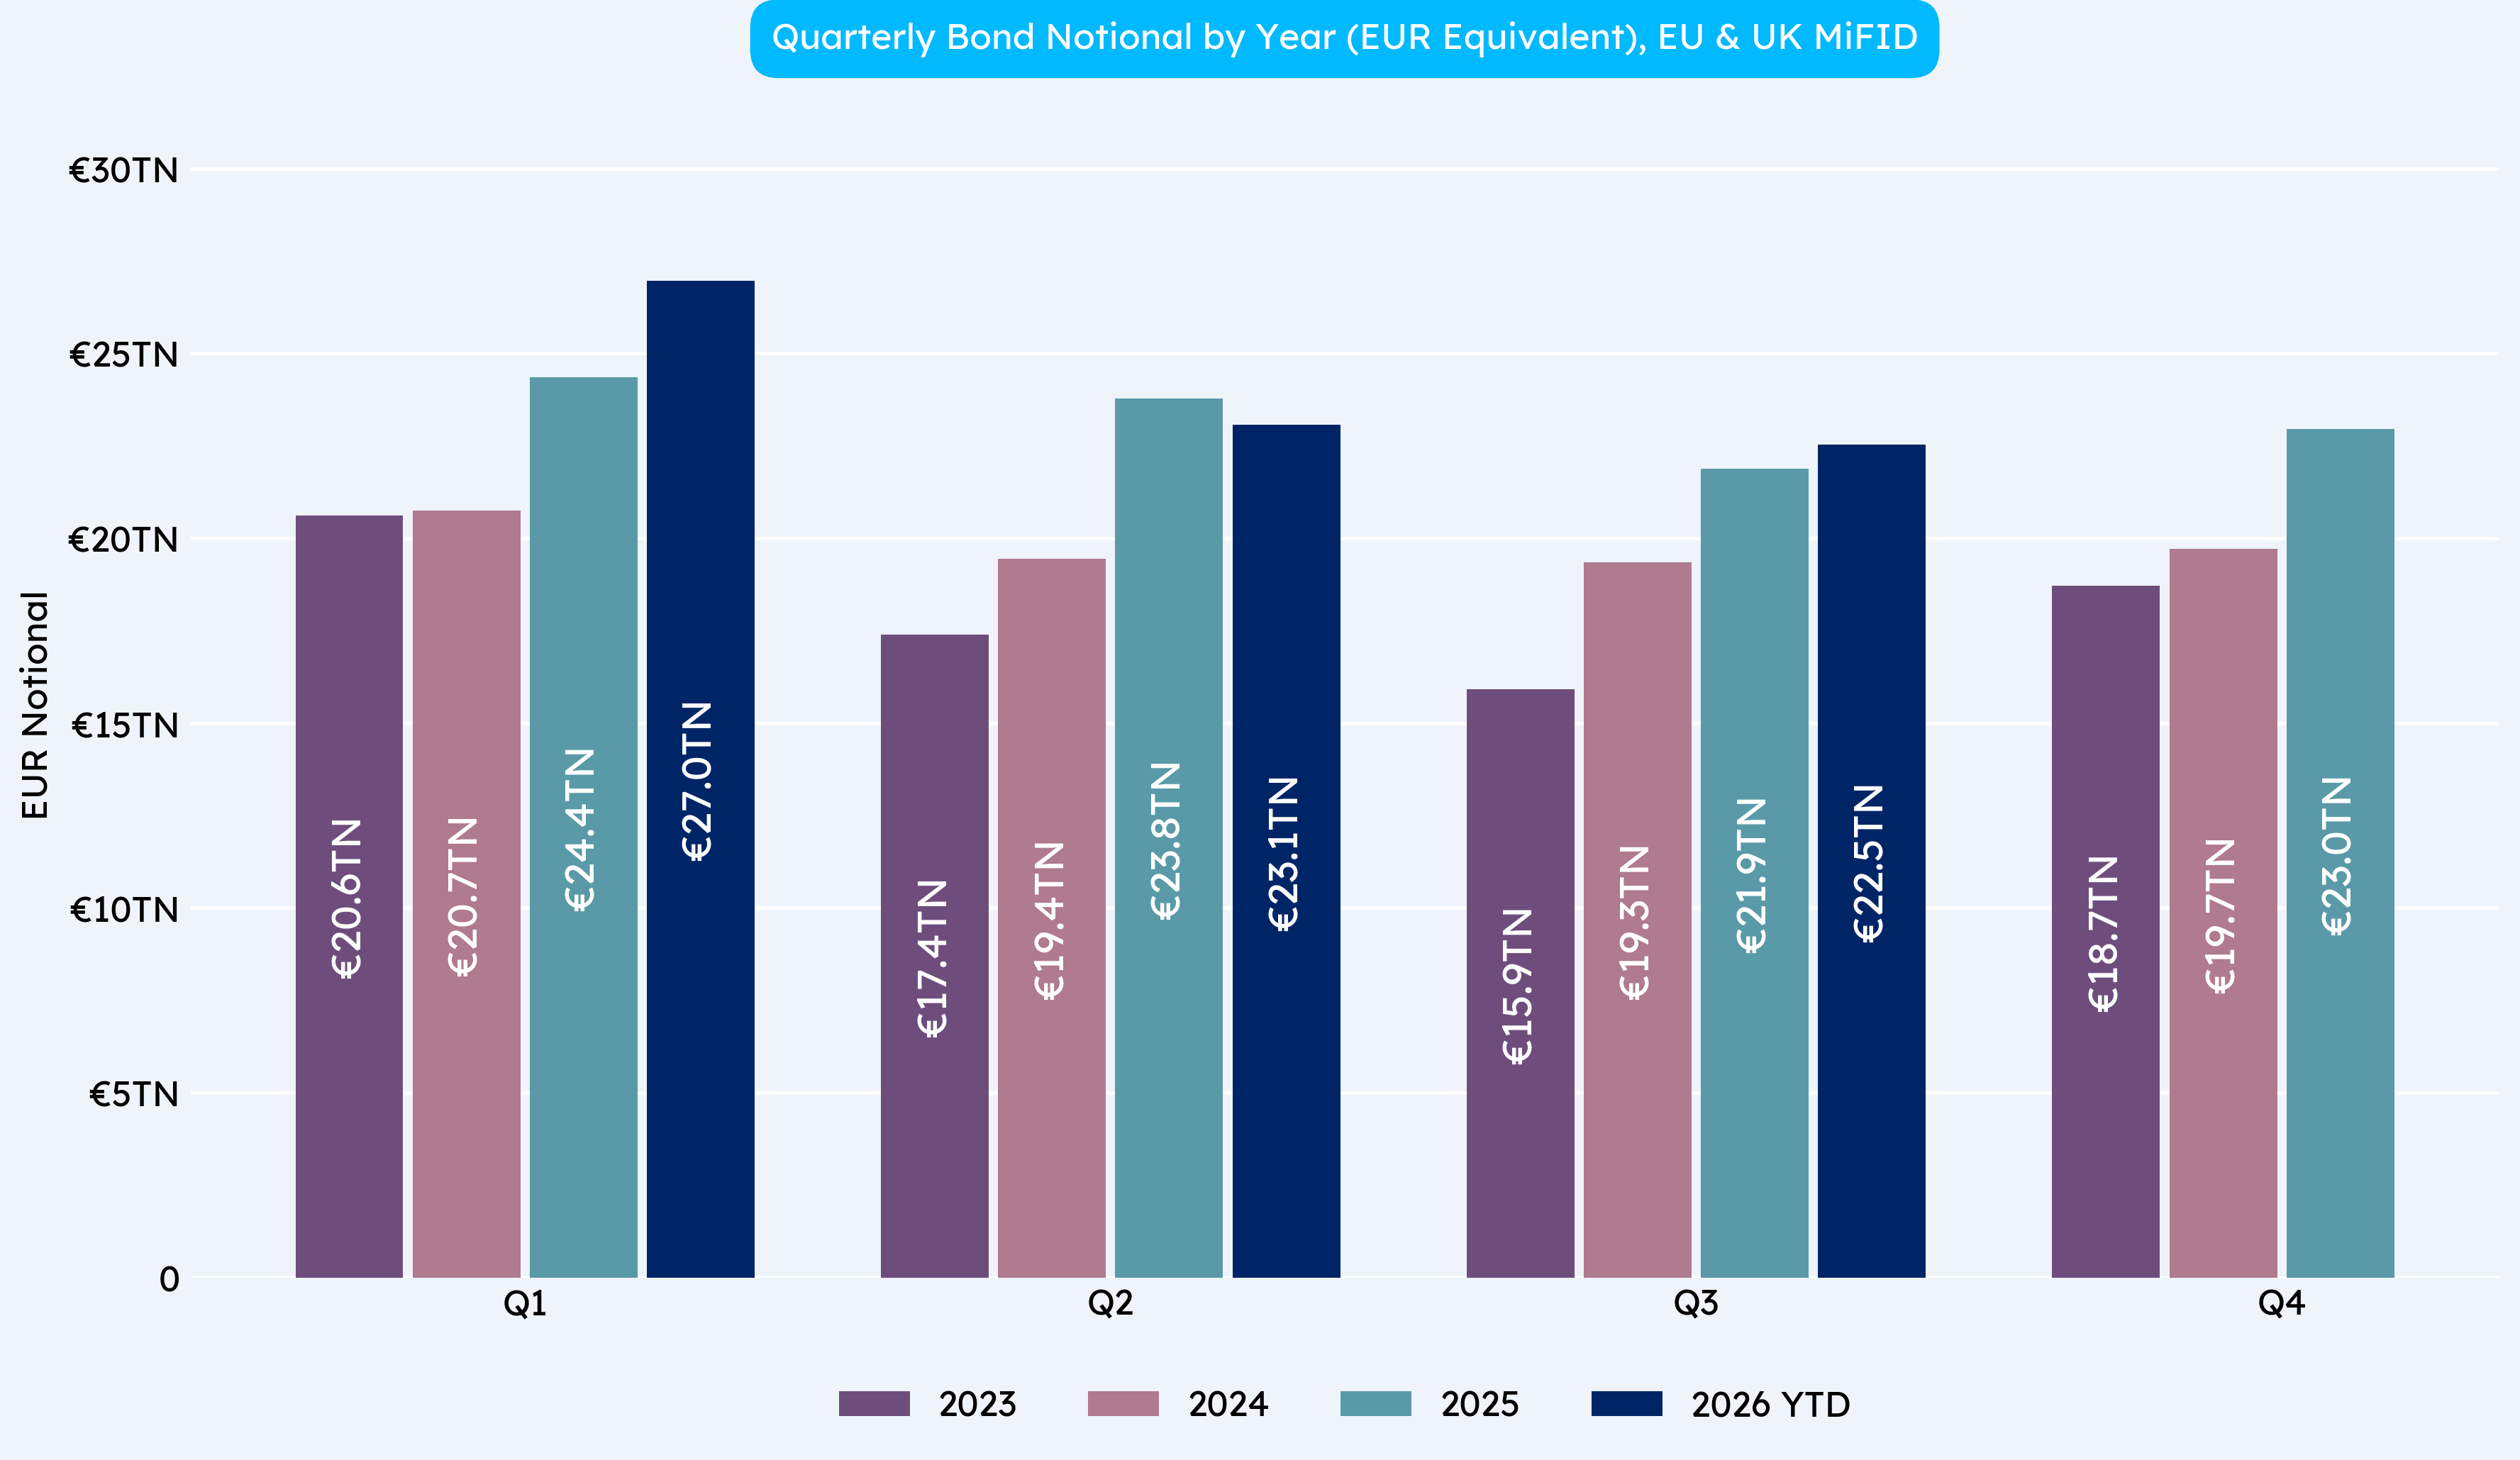
Chart 1 above shows us the distribution of volume over the last 4 years and it presents an interesting view.
We see that generally volumes drop ever so slightly in Q2 and Q3 compared to Q1 but do not significantly (if at all) increase again in Q4 across all years (noting, we don’t yet have volumes for Q4 of 2026).
Next we want to consider the data from a percentage viewpoint, i.e. if we look at the proportion, per quarter for each year, how does it look?
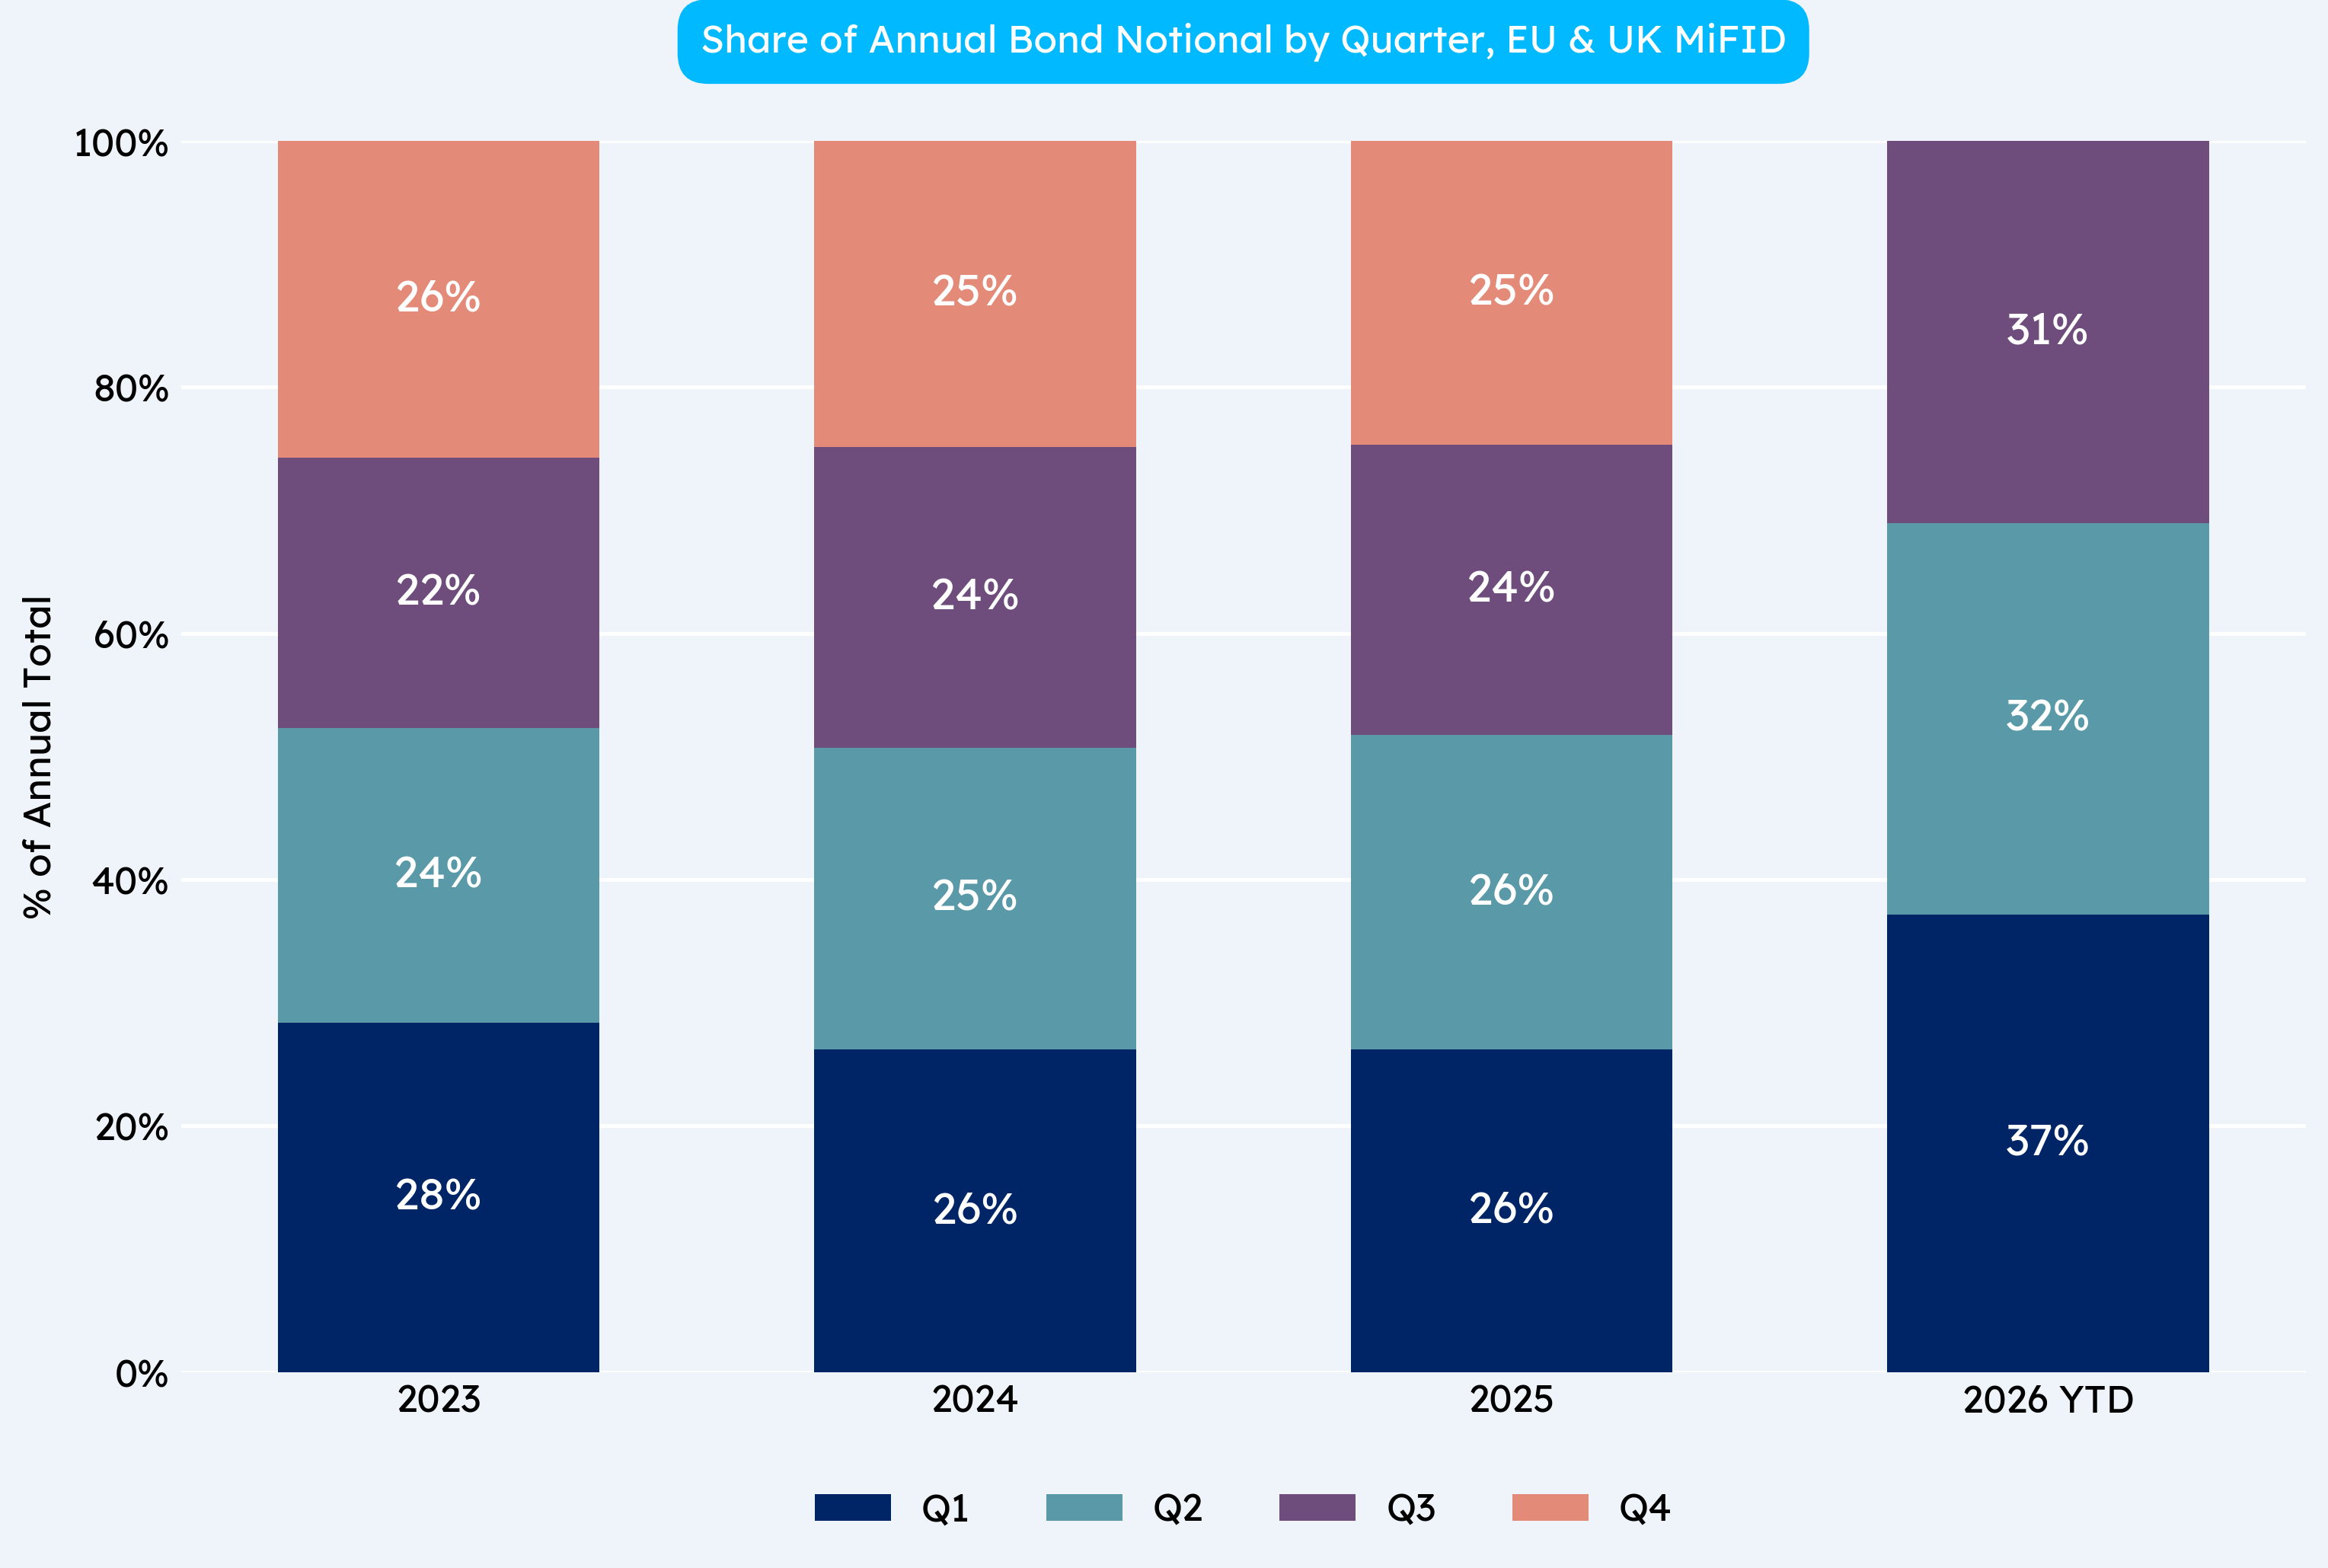
Chart 2 above re-confirms what we saw in Chart 1. It shows us that in all 4 years Q1 always has the highest volume, however the trend between Q2, Q3 and Q4 differs slightly.
What we can say with a degree of confidence is that Q1 is typically the most active quarter and Q3 is tycially the lowest.
The 2026 data is of course incomplete as at the time of writing we are in October 2026, therefore the percentages will change as we get closer to year end.
Finally we take a look at a monthly breakdown of volume for 2026, comparing sovereigns and corporates. It’s no surprise sovereigns make up the majority of volume.
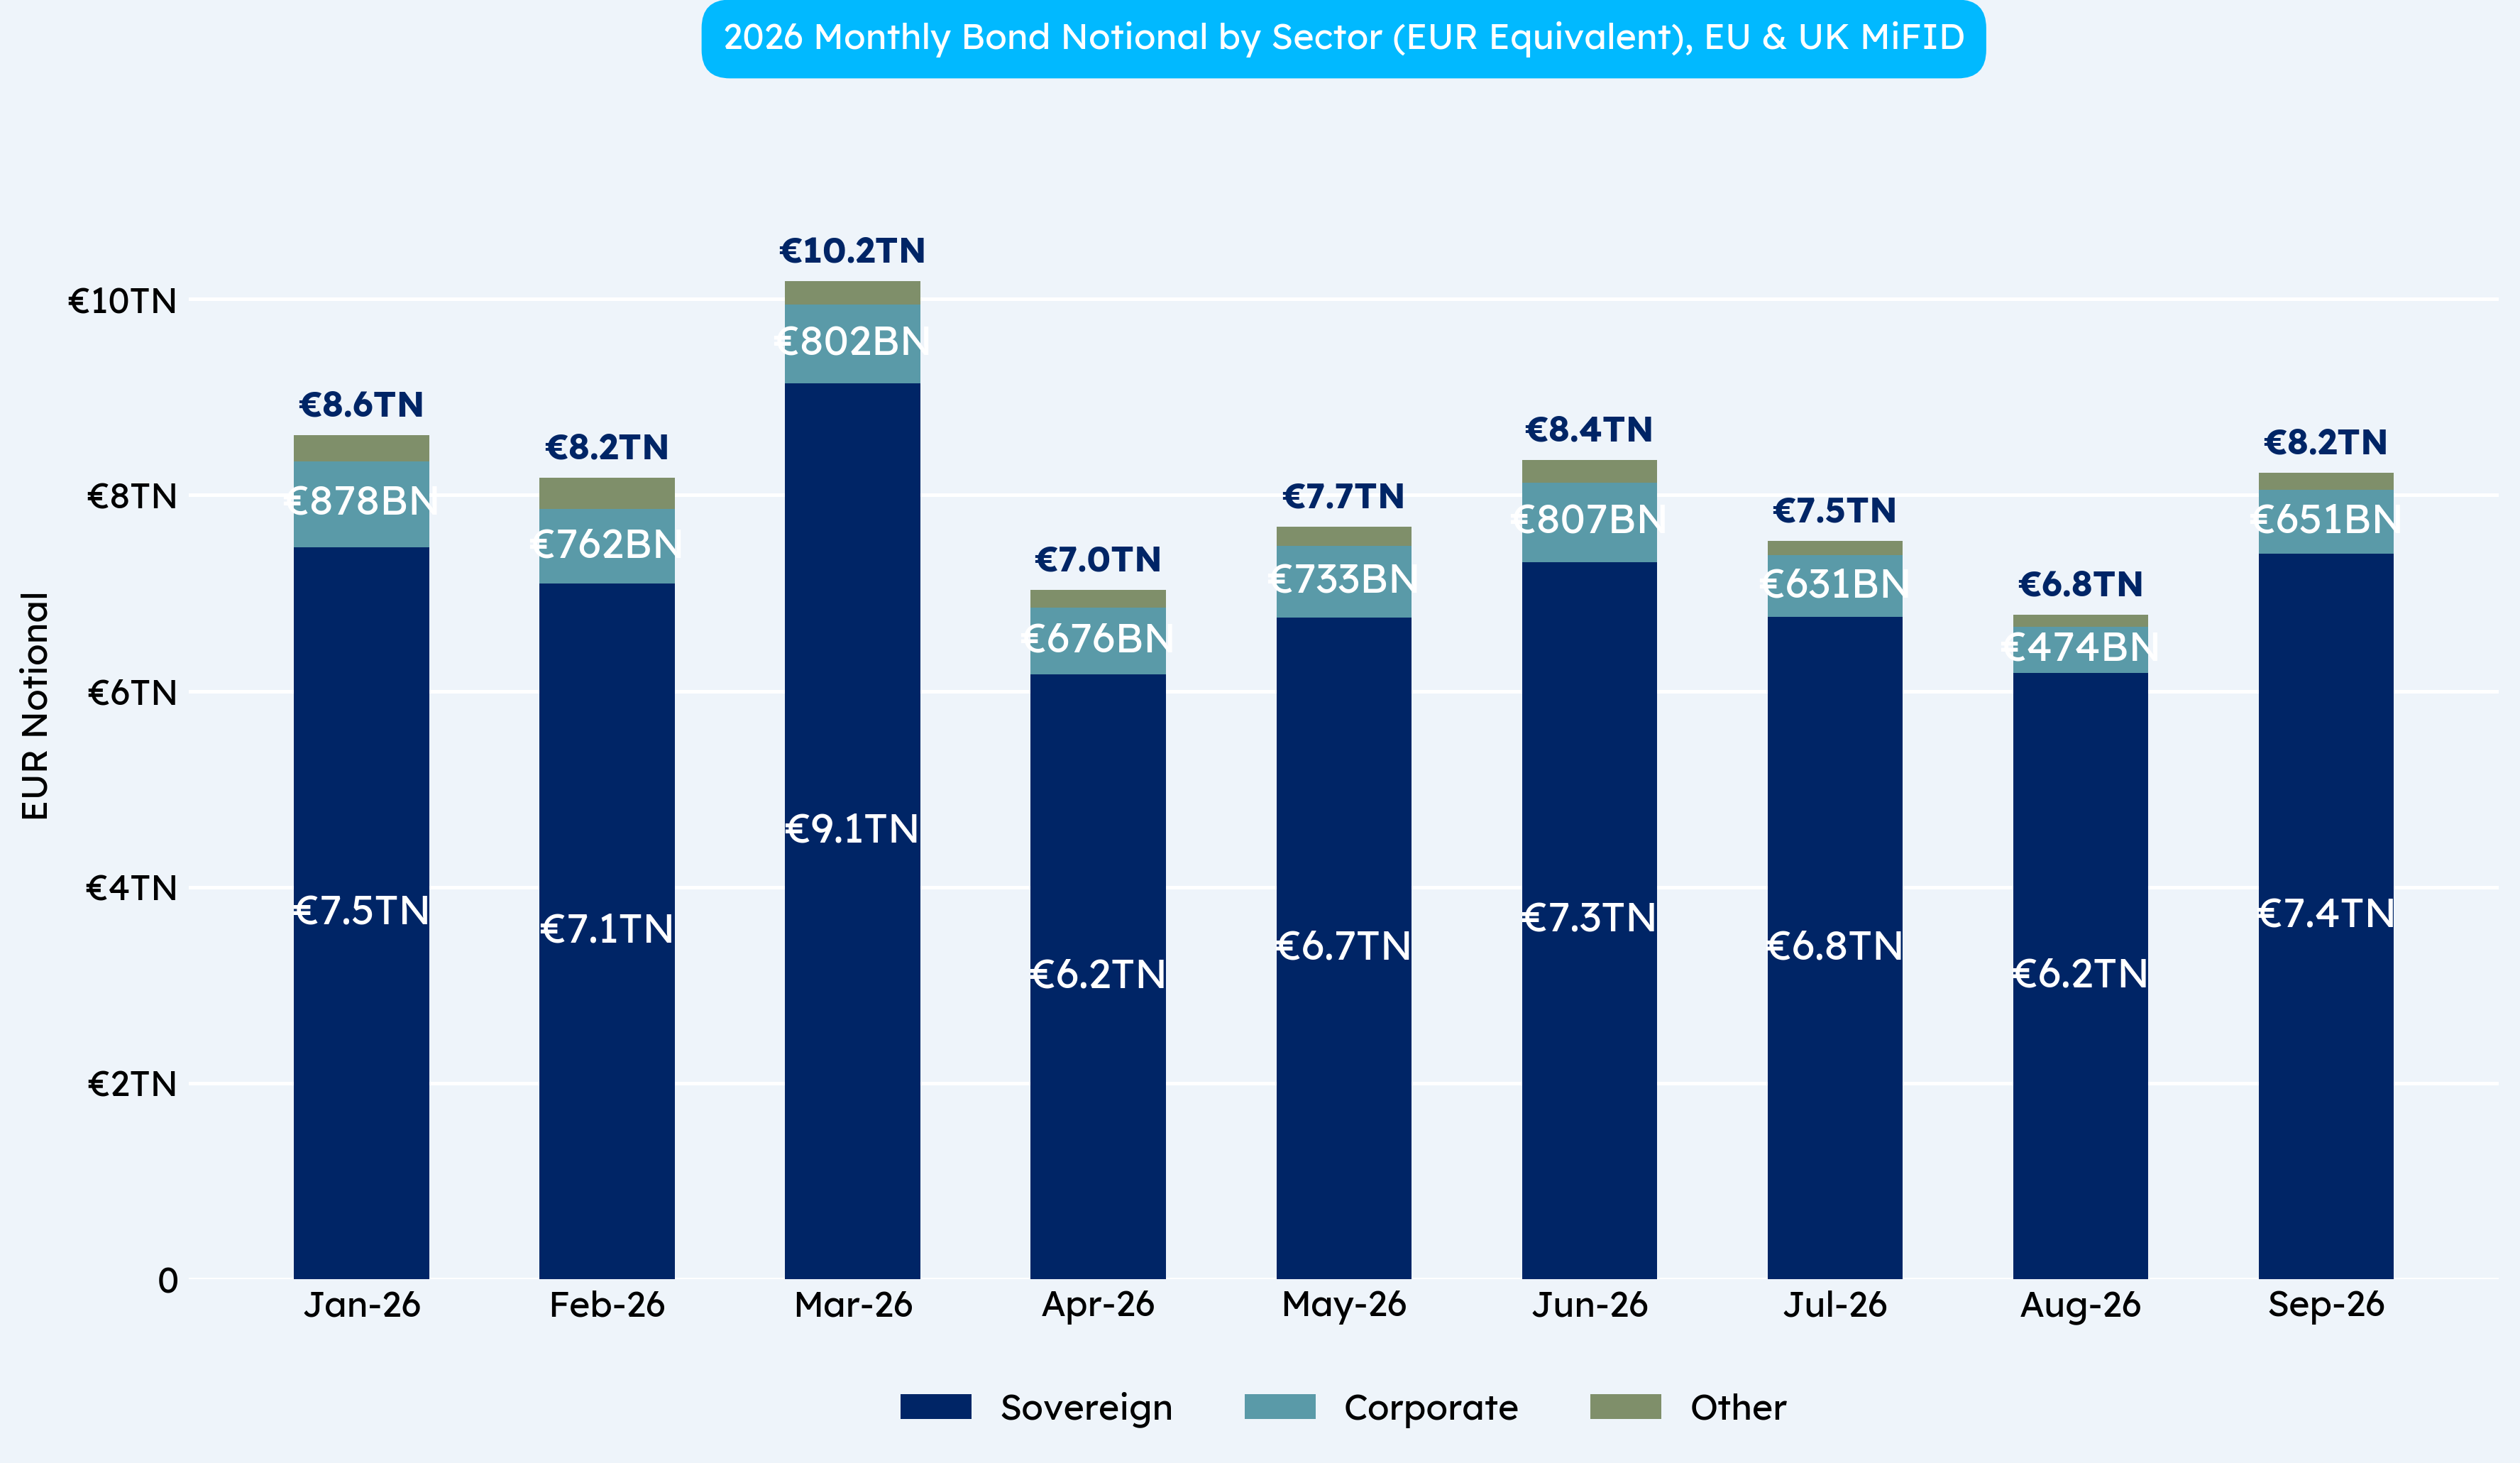
Chart 3 highlights that even though we can observe trends at a high level over the quarter, month by month trends are less obvious, with volumes falling and dropping potentially due to macro and geo-political trends such as the Iran conflict2, rather than mere seasonal adjustment.
“At first glance it looks as though March is a larger outlier and that September is fairly in line with summer months so it may appear the summer slump isn’t as pronounced as expected. However it is worth remembering, that (geo-political events aside) the EU regime went live in March so we might expect to see an increase in volume here. Also we haven’t seen a portion of September volume yet as as many deferred September trades for both EU and UK regimes are yet to be published.”
1https://www.hl.co.uk/news/sell-in-may-and-go-away-what-does-this-mean-for-investing-in-2024
2https://edition.cnn.com/interactive/2026/05/politics/iran-war-key-moments-vis/index.html
Vidal Mehra - Vidal is Chief Product Officer for Propellant Digital and the lead author for Propellant Insights.
He has been working with financial institutions for over 20 years across multiple disciplines including front office and consulting roles.
Helena Roughton - Helena recently joined the team as a Product Manager, bringing extensive MiFID policy experience having previously worked at AFME.
She also brings product remediation and data analysis experience from the Bank of New Zealand.